Form 5472 Penalty: What Triggers the $25,000 IRS Fine and How to Fix It
Last updated: 2026-08-18
The short version
TL;DR: If you own a US LLC and you are not a US citizen or resident, you almost certainly need to file Form 5472 every year. Missing the deadline triggers a flat $25,000 penalty per form, and it stacks for each related party you fail to report. The fix: file on time, keep clean records, and get help if unsure. doola handles this filing for non-US founders as part of its LLC compliance plan.What is Form 5472 and why does it matter for LLCs?
Form 5472 is the IRS information return required under IRC Sections 6038A and 6038C when a "reporting corporation" has reportable transactions with a foreign or domestic related party. It is not a tax return in the traditional sense. It tells the IRS about money flowing between your US entity and related foreign parties.
For tax years beginning on or after January 1, 2017, the IRS treats a foreign-owned US disregarded entity as a reporting corporation for Form 5472 purposes. A single-member LLC owned by a non-US person is a disregarded entity. That means your LLC has its own filing obligation even though it does not file a regular income tax return.
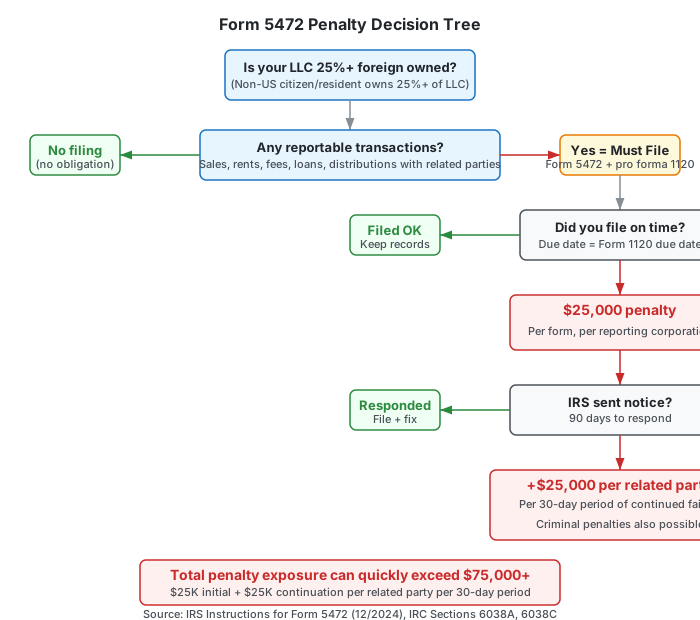
Do I actually need to file Form 5472 for my LLC?
You must file if your LLC is a "reporting corporation" and had a reportable transaction with a related party during the tax year.
25% foreign owned: Per the IRS instructions for Form 5472 (revised 12/2024), a corporation is 25% foreign owned if it has at least one direct or indirect 25% foreign shareholder at any time during the tax year. A foreign person is a 25% foreign shareholder if they own, directly or indirectly, at least 25% of either the total voting power or the total value of all classes of stock.
For a single-member LLC owned by a non-US person, you are the 100% foreign owner. You cross the threshold automatically. The constructive ownership rules of Section 318 apply with modifications, but for most single-member foreign-owned LLCs, the answer is yes.
The narrow exception: you do not need to file if you had no reportable transactions listed in Parts IV, V, or VI of the form. But if your LLC received any money from you, paid you distributions, or had any sales, rents, or service fees with you, you must file.
What triggers the $25,000 penalty?
The penalty is blunt and it stacks. Per the IRS instructions:
A penalty of $25,000 will be assessed on any reporting corporation that fails to file Form 5472 when due and in the manner prescribed. The penalty also applies for failure to maintain records as required by Regulations section 1.6038A-3.
Filing a substantially incomplete Form 5472 constitutes a failure to file.
Each member of a group of corporations filing a consolidated information return is a separate reporting corporation subject to a separate $25,000 penalty.
The continuation penalty is worse. If the failure continues for more than 90 days after notification by the IRS, an additional penalty of $25,000 will apply. This applies with respect to each related party for which a failure occurs, for each 30-day period (or part of a 30-day period) during which the failure continues after the 90-day period ends. Criminal penalties under IRC Sections 7203, 7206, and 7207 may also apply.
What are the most common reasons people get hit with the penalty?
- Not knowing the form exists. Many non-US founders set up an LLC through a formation service and never hear about Form 5472. Their CPA may not specialize in international tax.
- Filing late. The form is due by the due date of the income tax return, including extensions. For foreign-owned US disregarded entities, it must be attached to a pro forma Form 1120.
- Filing incomplete. The IRS explicitly states that a substantially incomplete Form 5472 constitutes a failure to file. Leaving Parts IV through VI blank when you had reportable transactions counts as incomplete.
- Not maintaining records. You must keep permanent books of account as required by IRC Section 6000. If the IRS asks and you cannot produce records, you face the same $25,000 penalty.
- Ignoring the IRS notice. If you receive a notice and do not respond within 90 days, the continuation penalty kicks in at $25,000 per related party per 30-day period.
What counts as a reportable transaction?
A reportable transaction is any transaction listed in Parts IV, V, or VI of Form 5472 for which monetary consideration was paid or received. For a typical single-member foreign-owned LLC:
- Sales or purchases of stock in trade
- Rents or royalties paid or received
- Consideration for services (management fees, consulting fees)
- Loans between your LLC and related foreign parties
- Distributions paid to you as the owner
- Amounts borrowed or loaned
There is no de minimis threshold. A $500 management fee is reportable.
When is Form 5472 due and where do I file it?
Form 5472 is due by the due date of the reporting corporation's income tax return, including extensions. For foreign-owned US disregarded entities, it is attached to a pro forma Form 1120. The pro forma requires only the name, address, and items B and E on the first page.
Request an extension by filing Form 7004. Write "Foreign-owned U.S. DE" across the top and file by the regular due date.
Foreign-owned US disregarded entities must file to a dedicated address:
Internal Revenue Service
1973 Rulon White Blvd
M/S 6112 Attn: PIN Unit
Ogden, UT 84201
Fax: 855-887-7737 (300 DPI or higher). Electronic filing is not available for disregarded entities.
How do I fix it if I already missed the deadline?
- File immediately. Do not wait for an IRS notice. The sooner you file, the less exposure to continuation penalties.
- File a complete form. Make sure all parts are filled in. If you had zero reportable transactions, still file and check the appropriate box.
- Gather your records. Bank statements, invoices, contracts, and transfer records documenting all transactions between your LLC and related foreign parties.
- Consider voluntary disclosure. For multiple years of non-filing, the IRS has procedures that may reduce penalties. A tax professional specializing in international compliance can help.
- Set up a system. The form is annual. Missing it again means the penalty stacks.
How can I avoid the Form 5472 penalty?
Avoidance comes down to three things:
Know the requirement. If you are a non-US founder with a US LLC, Form 5472 is not optional. It applies even if your LLC has no employees, no US customers, and minimal activity. The threshold is 25% foreign ownership plus any reportable transaction.
File on time every year. Put the deadline on your calendar. If you need more time, file Form 7004 before the deadline.
Keep clean records. Track every dollar that moves between your LLC and yourself or any related foreign entity.
For non-US founders who do not want to handle this themselves, doola manages Form 5472 filing as part of its LLC compliance and tax filing plan.
FAQ
Does a single-member LLC owned by a non-US person need to file Form 5472?
Yes. A single-member LLC owned by a foreign person is a foreign-owned US disregarded entity. The IRS requires such entities to file Form 5472 attached to a pro forma Form 1120 if they have any reportable transactions with a related foreign party.
What is the penalty for not filing Form 5472?
$25,000 per form, per reporting corporation. It applies for late filing, incomplete filing, or failure to maintain records. If the failure continues more than 90 days after IRS notification, an additional $25,000 applies per related party per 30-day period.
Can I file Form 5472 electronically?
Foreign-owned US disregarded entities cannot file electronically. You must file by mail or fax to the dedicated Ogden, UT address.
Is there a minimum dollar amount that triggers Form 5472?
No. Any monetary consideration paid or received between your LLC and a related foreign party is reportable, regardless of amount.
What if I had no transactions with a foreign related party?
You are not required to file if you had no reportable transactions in Parts IV, V, or VI. When in doubt, file. The penalty for not filing is far more expensive than filing a form with zero entries.
Recap
- Form 5472 is required under IRC Sections 6038A and 6038C for 25%+ foreign-owned US corporations, including foreign-owned LLCs treated as disregarded entities.
- The penalty is $25,000 per form for late filing, incomplete filing, or failure to maintain records.
- The continuation penalty adds $25,000 per related party per 30-day period after 90 days of IRS notification.
- Foreign-owned US disregarded entities must file Form 5472 attached to a pro forma Form 1120 by the due date (including extensions).
- File by mail or fax to the dedicated Ogden, UT address. Electronic filing is not available for disregarded entities.
- If you missed the deadline, file immediately and consider voluntary disclosure for multiple years of non-filing.
Sources: IRS Instructions for Form 5472 (12/2024), IRS About Form 5472, IRS International Information Reporting Penalties, IRS Form 5472 Instructions PDF (12/2024)
Get our free LLC Formation Checklist
Step-by-step guide: state fees, timelines, EIN process, and the exact paperwork checklist. Used by 200+ founders.
Download Free Checklist